Options Profit Engine
4/17/19
This Week’s Trade Recommendation Review:
Note: Trades listed here are from the last week and are listed for review purposes only. Any new trades issued will come as a separate trade alert.
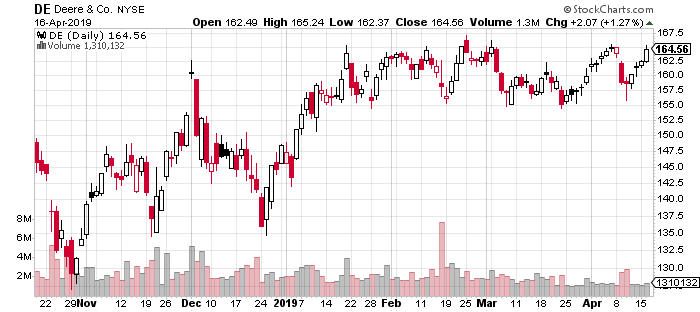
(From April 10th) Sold the Deere (DE) May 10th 146-150 put spread for a $0.68 CREDIT
Video link for trades over the last week:
https://content.jwplatform.com/videos/RoYstKFs-bK67iJnL.mp4
Trade Analysis:
It’s been a full week since we made the DE trade but we have quite a few positions on right now so I didn’t want to rush to add more of them. My current plan is to wait a few more days before adding another credit spread, but that may change based on opportunities that pop up. If I don’t add another trade this week (due to the short week with the market closed on Friday), then I’ll add both a credit spread and new market hedge as early as next Monday.
Regarding DE, it’s almost too good to be true. In fact, the trade worked so well that I’m not sure that many people actually got in it before the stock went up. Just a reminder, if you are someone who uses texting, please sign up for my text alerts so you can get the trades about 5 minutes after they happen. The trade alert emails have to go through my publisher and may take up to an hour to disseminate.
That being said, DE is doing very well for those who got in on time. The stock shot up the day of the trade, which is very fortunate timing. DE was cheap from a valuation perspective at least in part due to the negative impact the tariffs have had on agriculture. The low valuation along with falling volatility made it a great candidate for a put credit spread. So far, we’ve been spot on with this position.
Open Position Update:
| Position | Current Return |
| TTWO May 3rd 85-89 Put Spread | -9.6% |
| EA May 3rd 92.5-96.5 Put Spread | -35.7% |
| SPY April 18th 274-279-284 Put Butterfly (Hedge) | -97.7% |
| VXXB May 10th 23-26 Put Spread | -22.6% |
| DE May 10th 146-150 Put Spread | +16.3% |
Portfolio Commentary:
We have five open positions this week. Results are based on trading prices for April 17th.
TTWO May 3rd 85-89 Put Spread – If you hold this position and EA you’ve no doubt noticed video games stocks are selling off recently. To be frank, I’m not at all worried. I love the industry and I think this selling is temporary. I’d be willing to roll out both this and the EA position rather than take a loss. In the meantime, we still haven’t come too close to hitting the short strike in TTWO. We should be back in positive territory soon on this position.
EA May 3rd 92.5-96.5 Put Spread – Conversely, EA has been hit harder than TTWO due to some concerns over a possible data breach. As a result, we are at the bottom of our spread range. This is a rare circumstance where I have no desire to close this trade despite the strong down move. I think EA is an easy buy right here. If we don’t recover enough to make money on this trade by expiration, we will roll it. Honestly, I’m really not all that worried about this position despite the current losses. Be patient with this one.
SPY April 18th 274-279-284 Put Butterfly (Hedge) – The market has pulled back a little, but not enough to impact our hedge which expires this week. We’ll let this one go and put on something new next week. We’ll continue to keep our hedges as inexpensive as possible.
VXXB May 10th 23-26 Put Spread – Here’s another situation where I’m more than willing to be patient. Volatility moves up a lot quicker than it moves down. A couple days like today or one true down day and this trade will be a big winner. Also, it serves as sort of a hedge since VXXB moves inverse the market.
DE May 10th 146-150 Put Spread – Not much left to say about DE. It’s already almost a full winner since we made the trade last week. We’ll close it soon.
Volatility Review:
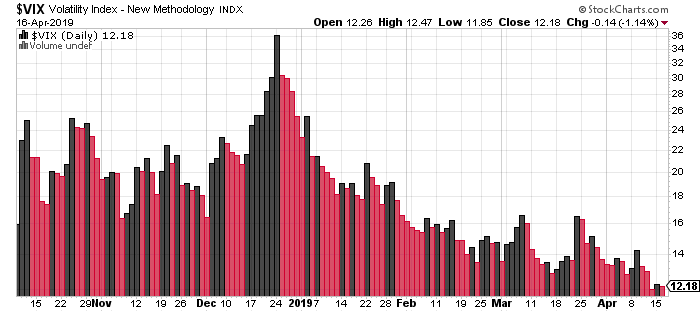
To date, I haven’t seen anyone else use a histogram to show VIX performance. I believe it’s a really good way to show how volatility moves. It’s particular useful today, as you can see just how far down we’ve come in market volatility in recent days. Compared to the end of last year, you can see we’re barely a blip on the graph with the VIX level around 12. The crowd is certainly complacent regarding the stock market right now and I don’t really disagree. Once again, I think we can afford to be more aggressive with our credit spreads and more patient with our existing positions.
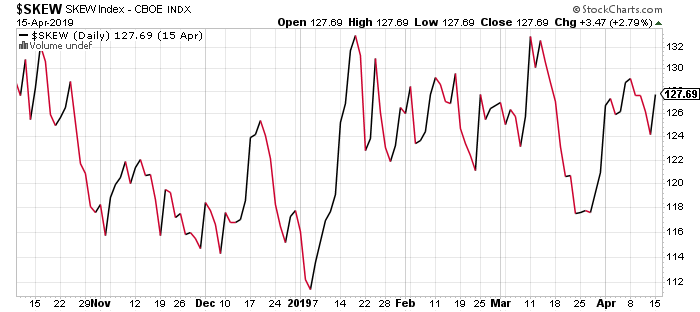
The SKEW level (OTM puts versus OTM calls) is also showing a non-event in the markets. There’s a steady level of put buying versus calls, so that suggests normal hedging is taking place by investors and funds. There isn’t a surge in put buying or monetizing of hedges going on beyond what is normal for this environment. Again, that suggests we don’t have a lot to worry about in the immediate future.