Options Profit Engine June 28, 2017 Issue
This Week’s Trade Recommendation: Sell the July 14th Nucor (NUE) 51.50-56 put credit spread for a $0.49 CREDIT.
Selling a put credit spread involves selling one put (the 56 put in this case) and buying another, cheaper strike in the same expiration period (the 51.50 strike). The short put should be closer to the stock price, while the long put is purchased further away (lower) and is used for protection. NUE is currently trading around $58. Feel free to sell down to around $0.40 on the put spread. I recommend doing a 5-lot trade, but you can alter your contract size based on the size of your account.
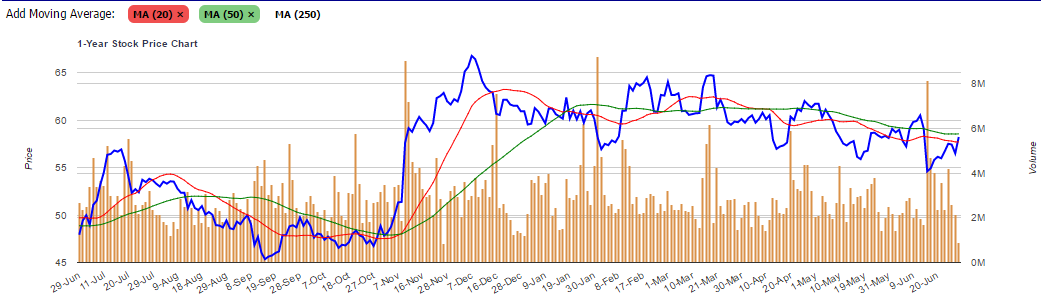
NUE isn’t likely to drop much in the next couple weeks due to upcoming earnings as well as strong fundamentals. However, implied volatility has recently been jacked up in options which expire prior to earnings, giving us an opportunity to sell put spreads.
Trade Analysis:
There’s some interesting volatility movement going on in steel stocks right now. There’s been a lot of positive news regarding US steel recently, and yet implied volatility has gone up at the same time. This dynamic is most obvious in Nucor (NYSE: NUE), one of the largest of the US-based steel producers. NUE is one of the few S&P 500 companies that actually looks undervalued at current levels. More importantly, the implied volatility is jacked to the point where selling a put spread is an easy choice to make for setting up a bullish position.
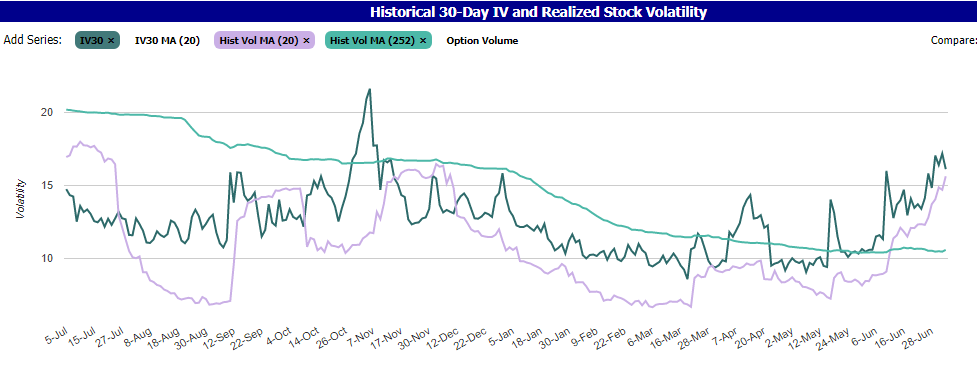
As you can see from the implied volatility chart above, implied volatility has climbed substantially higher than historical volatility – almost to the tune of a 10% gap – before narrowing the gap a bit today. Considering our options will expire before earnings, there’s no reason to believe this volatility spike is going to be associated with a lower move in the stock. What’s more, the fundamentals and analysts’ opinion on NUE is bullish. All in all, it points to a nearly ideal put spread selling opportunity.
So here’s the trade once again:
Sell the July 14th Nucor (NUE) 51.50-56 put credit spread for a $0.49 CREDIT.
Open Position Update:
Portfolio Commentary:
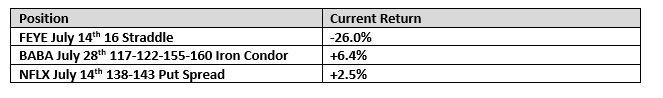
We have three open positions at the moment. Results are based on close of trading prices for Tuesday June 27th.
FEYE July 14th 16 Straddle – Time decay continues to take its toll on this straddle. We need FEYE to be under $15 for the value of the options to counteract what we’ve lost from time. Now, we still have over two weeks to expiration, and FEYE could easily drop below $15 in a day. So, we’ll continue to monitor the trade closely, and I’ll look to close it after the July 4th holiday if the stock hasn’t moved substantially by then.
BABA July 28th 117-122-155-160 Iron Condor – The BABA iron condor continues to perform exactly as expected. The stock remains right in the middle of our price range, which is an ideal situation for a short iron condor. After the July 4th holiday, we should start seeing an uptick in time decay (which is good for us in this case) and then we’ll look to close out the trade for a profit.
NFLX July 14th 138-143 Put Spread – The NFLX put spread is exactly where we want it to be. We’re sitting at $154, with just over two weeks to go to expiration, including a holiday. By next week, the return will increase daily even if the stock doesn’t move. We’ve probably got about a week before we’ll look to close this trade (with a very high probability of it being a winner).
Market Overview:
The past week of market news has centered on the future of interest rates and health care. Fed Chair Yellen believes the US economy can sustain higher rates despite some recent weakness in economic news. There’s no indication the Fed plans on changing its current policy (which basically calls for one more rate hike this year), but Yellen did refer to current stock valuations as “somewhat rich”. Obviously the situation bears paying attention to. From a health care standpoint, the Senate does not have the votes it needs to pass the recent health care bill in its current form. As such, the vote for the bill is on hold for the time being, leaving the health care sector in a continued state of limbo.
Volatility Review:
While the health care situation isn’t doing much to alter the state of volatility, the interest rate scenario is having a greater impact on VIX levels. Yes, overall volatility remains historically low. However, since the Fed has made it clear rates will be going higher, we haven’t seen the sub-10 VIX nearly as often as in prior weeks.
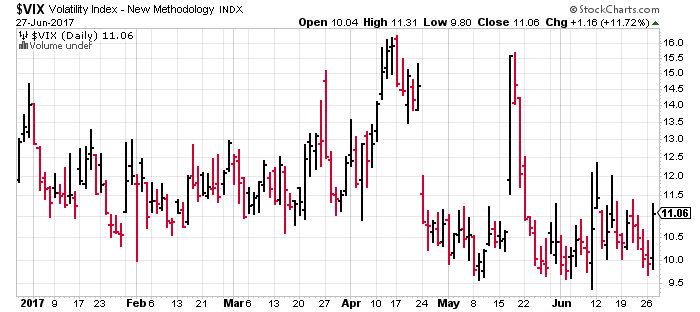
Due to the heart of summer vacation season around the corner, I don’t expect a serious jolt in volatility anytime soon. Yet, it does look like the base volatility scenario is going to be about 5% to 10% off recent lows. Once again, it could be a sign that the days of super ultra-low volatility are coming to end (and instead we’ll just have ultra-low volatility instead, without the extra super). In other words, I’m not suggesting the secular volatility sellers are about to get run over – but I certainly think investors should start thinking about how to protect their portfolios in the event of higher volatility.
That being said, we have come across an excellent volatility selling opportunity which has little or nothing to do with the overall volatility picture. The steel industry is experiencing higher volatility (possibly due to comments from the White House), while analysts tend to still be bullish on most steel stocks. That’s a perfect opportunity to sell an out-of-the-money put spread, just like we’re doing with NUE.