As I write this, about two-thirds of the Velocity Report portfolio stocks have reported their second-quarter earnings. Here are some of the highlights.
Diamondback Energy (FANG) reported earnings of $6.48 per share, up from $4.23 for the first quarter. The company declared a $1.10 dividend.
Marathon Petroleum Corp (MPC) had blowout earnings that were up 400% year over year. You can read about MPC in this newsletter issue.
Valero Energy (VLO) had a massive earnings beat, reporting profits of $12.54 per share, up from $4.22 for the first quarter.
Farmer Mac (AGM) reported earnings of $5.40, beating the Wall Street estimate by $0.53. AGM reported earnings of $4.74 for the first quarter.
AbbVie (ABBV) reported earnings of $3.65 per share, up from $2.65 for the first quarter. Full-year guidance was updated to $13.91, to $14.11 per share.
VICI Properties (VICI) reported FFO of $0.62 per share. This was down from $0.82 for the first quarter.
Antero Midstream (AM) reported net income of $0.27 per share. This was down from $0.29 for the first quarter.
Bank OZK (OZK) reported net income of $1.49 per share, compared to $1.44 reported for the first quarter.
Liberty Energy (LBRT) reported earnings of $0.26 per share. Revenue of $1.2 billion was up 14% year over year.
CME Group (CME) reported earnings of $2.99 per share, compared to $3.36 for the first quarter. The second-quarter results beat the Wall Street consensus.
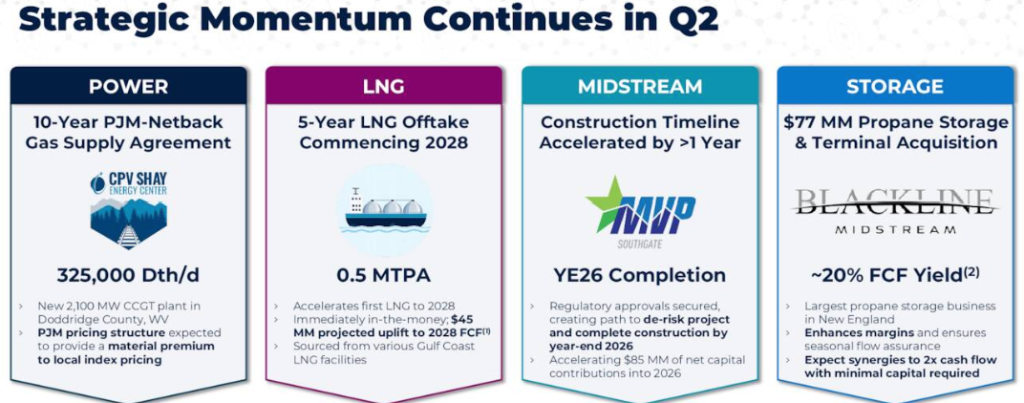
EQT Corp (EQT) reported EBITDA of $1.07 billion and free cash flow of $330 million. EQT has several growth channels getting underway as shown in this graphic:
As of the end of July, we have a couple of pairs of stocks with each pair going in the opposite direction.
Through July, almost everything associated with artificial intelligence sold off. Our two AI infrastructure stocks followed suit. LBRT is off 28% since the end of June. Still, for the last 12 months, the stock is up 72%. Kodiak Gas Services (KGS) is down 23% since June 30. It’s still up 59% year to date.
Our two refinery stocks are doing very well. MPC is up 20% since June 30 and 92% year to date. For the same time frames, VLO is up 18% and 89%, respectively.
The large share price swings benefit us through our quarterly rebalancing.
Notes
Be sure to mark your calendar for our two events this month.
Monthly video mailbag: recorded and sent to you via email on the second Wednesday of every month just after 6:00 p.m. eastern. In it I answer your questions and those of other subscribers. You can watch the most recent mailbag here and send your questions for the next one here.
Live monthly webinar: we’ll discuss our portfolio stocks and strategy along with updates. There will be time for your questions. The webinar starts at 4:30 p.m. on the fourth Wednesday of the month.The next one will be August 26th. Save this link to join us then: https://us02web.zoom.us/j/89682189402. Hope to see you there!
I’ve had a few subscribers ask me about my Daily Dividends income plan. It’s not part of Velocity Report, rather an integral part of ETF Income Edge, my high-yield income ETF newsletter.
Daily Dividends works by using just five ETFs to get you paid every day the market’s open – Monday through Friday. The best part is I do everything for you – monitor the funds in the program, alert you to any adjustments… everything. All you have to do is place the trades and watch dividends hit your account every day. Plus, you can start with as little as $200 if you just want to test it out first. Watch my new presentation that gives you all of the math and other details on how Daily Dividends could be just what you’ve been looking for. Click here.
Marathon Petroleum Corporation
Business Overview
Marathon Petroleum Corporation (MPC) is a leading integrated downstream and midstream energy company headquartered in Findlay, Ohio. It operates the nation’s largest refining system, with approximately three million barrels per calendar day of crude oil refining capacity across 13 refineries located primarily in the Gulf Coast, Mid-Continent, and West Coast regions. These facilities process crude oil and other feedstocks into a broad slate of refined products, including gasoline, diesel, jet fuel, heavy fuel oil, asphalt, propane, and various petrochemicals. The company distributes these products through an extensive logistics network of pipelines, terminals, barges, and trucks, selling them to wholesale customers domestically and internationally, on the spot market, and to independent operators of Marathon-branded outlets as well as through long-term supply contracts with direct dealers that primarily operate under the ARCO brand.
MPC’s midstream operations are conducted primarily through its ownership of the general partner and a majority limited partner interest in MPLX LP, a master limited partnership. MPLX gathers, transports, stores, and distributes crude oil, refined products (including renewable diesel), and other hydrocarbons via refining logistics assets, pipelines, terminals, towboats, and barges. It also gathers, processes, and transports natural gas while fractionating, storing, and marketing natural gas liquids, with significant capacity that includes roughly 11.2 billion standard cubic feet per day of natural gas processing and substantial NGL fractionation capability. This midstream network is tightly integrated with MPC’s refining system, enabling efficient feedstock supply, intermediate product transfers between refineries, and product distribution that supports operational flexibility and margin capture across the value chain.
Complementing its traditional refining and logistics activities, MPC maintains a Renewable Diesel segment that processes renewable feedstocks into renewable diesel at facilities such as those in Dickinson, North Dakota, and Martinez, California. The company has several renewable fuel and feedstock facilities with hundreds of millions of gallons of annual production capacity and has delivered substantial volumes of renewable fuels in recent years. Overall, MPC’s business model emphasizes scale, regional integration of refining and midstream assets, commercial optimization of product yields and sales channels, and growing midstream cash flows from MPLX, positioning it as a major supplier of transportation fuels and related energy products in the United States while expanding into lower-carbon intensity fuels.
Investment Considerations
Year to date, the story for refining companies revolves around the Iran conflict and the closing of the Strait of Hormuz. About one-fifth of the world’s crude oil ships, or at least did ship, through the strait and a large portion of global refined products. The resulting global shortages allowed the U.S. refining companies to expand their profit margins greatly.
The increase in profits showed up in the recently released MPC second quarter earnings results.
For the quarter, the company reported EPS of $17.73, beating the Wall Street consensus forecast by $3.78. For the 2025 second quarter, MPC earned $3.96 per share. Earnings for the recent quarter were four times higher than a year earlier.
Cash and cash equivalents totaled $7.77 billion at the end of the quarter, up from $2.15 billion a year earlier. The cash hoard is after Marathon spent $2.53 billion on share buybacks.
The Wall Street estimate for third-quarter earnings is $17 per share, with all 14 analysts that follow the company increasing their estimates over the last 90 days.
Eventually, as the world energy situation gets back to more “normal” supply and demand, profit margins for refiners will shrink from the current very high levels. Several factors about Marathon Petroleum keep me positive about the long-term returns from this stock.
The midstream earnings from the MPLX holdings provide a stable source of income. For the quarter, MPLX chipped in EBITDA of $1.78 billion, up 8.3% from a year earlier. For reference, total EBITDA for the second quarter was $8.46 billion, and $3.29 billion for the 2025 second quarter.
Marathon’s policy of using excess cash flow to buy back shares has led to a significant reduction in the share count, which mathematically increases the earnings per share from the same amount of gross profit. Over the last three years, the share count has been reduced by 31%.
MPC is up 90% year to date and up 20% quarter to date. Our quarterly rebalancing at the end of September will allow us to scrape off some of those profits.
Portions of this article were written with the assistance of a large language model (LLM). The article has been vetted and edited by the Investors Alley editorial team. Tim Plaehn wrote the investment analysis.
Simon Property Group
Business Overview
Simon Property Group, Inc. (SPG) is a self-administered and self-managed real estate investment trust (REIT) headquartered in Indianapolis, Indiana. It owns, develops, and manages premier shopping, dining, entertainment, and mixed-use destinations, primarily consisting of regional malls, Premium Outlets, and The Mills centers. As of late 2025, the company owned or held interests in approximately 212 income-producing properties in the United States (including 108 malls, 70 Premium Outlets, 16 Mills, six lifestyle centers, and other retail properties across 38 states and Puerto Rico), along with interests in about 42 international properties mainly in Asia, Europe, and Canada. It also holds a roughly 22% equity stake in Klépierre SA, a major European shopping center owner, and has fully consolidated interests such as those from The Taubman Realty Group.
The core of Simon’s business revolves around generating lease income from a high-quality portfolio of retail real estate. Revenue comes primarily from fixed minimum rents and common area maintenance reimbursements paid by tenants, supplemented by variable rents based on tenant sales, as well as reimbursements for taxes, utilities, and marketing. The company focuses on Class A properties in strong trade areas with high retailer sales productivity (often exceeding $700–$800 per square foot), high occupancy rates (around 96% for U.S. malls and Premium Outlets), and continuous remerchandising and redevelopment to incorporate experiential retail, dining, entertainment, residential, and hospitality elements. This strategy supports rent growth, traffic, and long-term net operating income while adapting traditional malls to evolving consumer preferences.
Beyond pure real estate ownership, Simon actively develops, redevelops, and expands properties; manages leasing and operations; and pursues selective acquisitions and joint ventures to enhance its portfolio. International operations and investments (including Premium Outlets and Designer Outlets abroad) contribute meaningfully to portfolio net operating income. In contrast, additional platform investments support retail operations, e-commerce, and real estate management. Overall, Simon’s model emphasizes scale in dominant retail destinations, disciplined capital allocation toward high-return redevelopments and densification, and a strong balance sheet that enables consistent cash flow generation and dividends as a leading retail REIT.
Investment Considerations
With a well-run REIT, the investment thesis is the classic dividend growth story. The thesis goes that the compounding annual total returns will, over time, be very close to the average dividend yield plus the average dividend growth rate.
Like the majority of REITs, Simon slashed its dividend during the pandemic. No one was going to the mall. But starting with the second quarter of 2021, the SPG dividend has increased quarterly, going from $1.30 per share to $2.25 per, share paid on June 30 of this year. That works out to 73% growth over five years—11% compounding growth. (We love compounding returns!)
The current yield is 3.93%. Over the last five years, the yield has ranged from 4.0% to 6.0%.
The average annual return from SPG since June 2021 was 15.3%. The dividend growth thesis and math work with SPG.
Portions of this article were written with the assistance of a large language model (LLM). The article has been vetted and edited by the Investors Alley editorial team. Tim Plaehn wrote the investment analysis.
Portfolio Update
Dividend Changes
On July 1, Bank OZK (OZK) declared a $0.48/share quarterly dividend, a 2.1% increase from prior dividend of $0.47. This dividend was paid on July 30; ex-dividend was July 13.
Here is a rundown on the current dividend status for each of the Velocity Report portfolio stocks:
Abbvie Inc. (ABBV) declared a $1.73 dividend on June 18. Payment is August 14; ex-dividend was July 15. The current yield is 2.82%.
American Financial Group (AFG) declared a $0.88 dividend on July 1. Payment was July 24; ex-dividend was July 15. The current yield is 4.95%.
Federal Agricultural Mortgage Corp. (AGM) declared a $1.60 dividend on May 14. Payment was June 30. The current yield is 2.69%.
Antero Midstream (AM) declared a $0.225 dividend on July 15. Payment is August 12; ex-dividend was July 29. The current yield is 4.09%.
CME Group Inc. (CME) declared a $1.30 dividend on May 7. Payment was June 25. The current yield is 4.26%.
EQT Corporation (EQT) declared a $0.165 dividend on July 15. Payment is September 1; ex-dividend is August 5. The current yield is 1.23%.
Diamond Back Energy, Inc (FANG) declared a $1.10 dividend on August 4. Payment is August 20; ex-dividend is August 13. The current yield is 2.21%.
Fidelity National Financial (FNF) declared a $0.52 dividend on May 7. Payment was June 30. The current yield is 4.03%.
Kodiak Gas Services (KGS) announced a $0.49 dividend on May 8. Payment was May 28. The current yield is 3.38%.
Liberty Energy (LBRT) announced a $0.09 dividend on July 15. Payment is September 18; ex-dividend is September 4. The current yield is 1.90%.
Marathon Petroleum Corp (MPC) declared a $1.00 per share dividend on July 29. Payment is September 10; ex-dividend is August 19. The current yield is 1.30%.
Bank OZK (OZK) announced a $0.48 dividend on July 1. Payment was July 20; ex-dividend was July 13. The current yield is 3.71%.
Royal Gold, Inc (RGLD) declared a $0.475 per share dividend on May 21. Payment was July 16; ex-dividend was July 2. The current yield is 0.94%.
InfraCap Small Cap Income ETF (SCAP) declared a $0.25 monthly dividend on July 29. Payment was July 31; ex-dividend was July 30. The current yield is 7.22%.
Simon Property Group (SPG) announced a $2.25 dividend on May 12. Payment was June 30. The current yield is 3.93%.
VICI Properties Inc. (VICI) announced a $0.45 dividend on June 4. Payment was July 9. The current yield is 6.78%.
Valero Energy Corporation (VLO) announced a $1.20 dividend on July 16. Payment is August 31; ex-dividend was July 31. The current yield is 1.56%.