
5 Stocks to Buy Now for a Lifetime of Increasing Dividends
– Tim Plaehn, Editor, The Dividend Hunter
When you start looking for stocks to generate income, it’s easy to focus on yields, and your temptation might be to believe that higher yields are always better. I too am a fan of high-yields, but only when the dividends come from a sustainable business model and the market is mispricing the quality of the company which leads to the higher yield.
 However, to build an income stock portfolio that is not subject to large swings in the stock market, you need to employ some portfolio management strategies beyond just investing in a handful of high-yield stocks.
When I speak with investors, either at investment conferences or through my newsletter or email, I focus on how we really can’t foresee when the market will correct or go into a bear market. These events are part of investing in stocks and happen on a regular basis, but the one thing I do know is that the market always recovers from a downturn. This is a key fact to remember when investing.
For income-focused investors specifically, investing in stocks that will keep the dividends coming through all stock market conditions is an utmost necessity. As you build an income stock portfolio, take the necessary steps to make sure you earn a stable and growing income stream through any market conditions.
Before I jump into a specific stock discussion to make the point and provide an attractive stock opportunity, here are a couple of basic portfolio strategies you should always have in mind as you research for stocks to add to your portfolio.
- Diversify across a number of stocks you own and by economic sectors. I recommend that about 20 stocks will give an adequate amount of diversification. This number needs to be spread across different market sectors such as equity REITs, financial companies (REIT or otherwise), energy, telecom, and transportation.
- Plan to reinvest a portion of your dividends, even if you are investing for income to pay your living expenses. The nice thing is you can still have a relatively high take-home yield even if you reinvest a portion of the dividends you earn. For example, Starwood Property Trust, Inc. (NYSE: STWD) currently yields about 11%. Taking 7% as income still leaves you 4% to reinvest. That reinvestment will buy more shares, giving you higher dividend payments the next time around and in the future.
- Look for dividend growth. Invest a portion of your portfolio – at least a quarter and up to half – in income stocks that are more focused on dividend growth than current yield. I like to call investments like these “Accelerating Dividend Stocks” because of their commitment to regularly increasing their dividends. The power of an accelerating dividend for driving total returns is why I recommend stocks like these.
This last point is important. Income focused investors tend to go for higher yields but do not spend a lot of time looking at dividend growth prospects.
There are a couple of reasons why dividend-focused investors need some growth prospects in their portfolios. First, high-yield stocks which do not have much dividend growth tend to have more volatile share prices. During the first two months of 2016, we all felt the pain of share prices that are down 20% or more even though the businesses behind the share prices are doing fine. You will find that by owning some stocks that generate higher dividend growth rates, you will get more price stability when the markets get volatile. Second, with some dividend-growth focus, you will also see share prices increase, generating higher wealth along with a higher income.
Our first example of a stock price charting an upward trajectory with increasing dividends is Tanger Factory Outlet Centers (NYSE: SKT). The chart below shows this clearly.
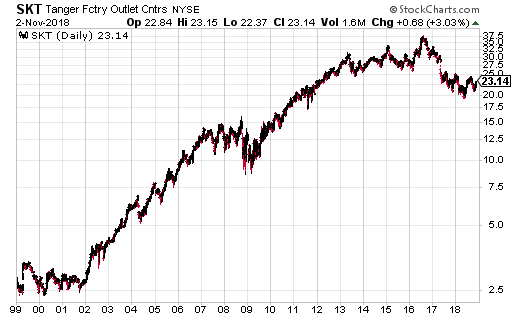
Tanger Factory Outlet Centers Inc. is the type of dividend growth stock you should own in your income-focused portfolio. While SKT shares currently yield just 3%, you need to look at the long-term potential from a company that grows its dividends like Tanger Factory Outlet Centers.
Here are some of the numbers:
- SKT has increased its dividend every year since going public in 1993.
- The company currently pays out about 60% of free cash flow, called funds from operations or FFO in the REIT world, as dividends with the rest staying in the company and used to grow future cash flow and dividends.
- The SKT dividend has grown by 7.4% per year compounded over the last 10 years and 11% annually over the last five years. This is a company that is accelerating its cash flow growth.
Let’s look at what your investment results would have been if you invested in Tanger 20 years ago. Remember, there have been two major bear markets in that period. On February 13, 1996, SKT closed at $26.25 per share. To buy 500 shares would have cost $13,125. Based on the last dividend before the purchase date, SKT was yielding 1.9%, resulting in $250 a year of dividend income.
Now we jump ahead 20 years to the present. There have been a pair of 2-for-1 share splits, so the position is now 2,000 shares. The current share price is $30.23, giving a share value of $60,460. The current annual dividend rate is $1.14 per share, giving an annual dividend amount of $2,280.
 To break it down, the SKT share value has increased by 460% and the dividend cash flow has grown by 912%. The $2,280 of annual dividends also represents a 17% annual yield on the initial investment amount.
Most income-focused investors buy dividend stocks because they are building an income stream for retirement or are already there and need the income from their stock portfolio. For most retirees, that stage of life will last for 25 years, 35 years, or even longer. A high-yield right now looks good to help pay your current expenses, but you also need to think about your income stream 20, 25, and 30 years in the future. Mixing in some stocks with average current yields but great dividend growth prospects will make sure those later retirement years are as good as the ones just around the corner.
Related: See Tim Plaehn’s new system for booking safe 16% returns every year.
While SKT has been an exemplary “Accelerating Dividend” stock to own for the last 20 years and is still a great buy, I am always looking for new opportunities in dividend growth stocks.
A strategy I use to search out profitable investments is to look for strong macroeconomic trends dominating a sector and then cherry pick the top stocks for dividend growth operating in that space. Right now, I am finding compelling “Accelerating Dividend” investments in the e-commerce space that Amazon.com, Inc. (NASDAQ: AMZN) currently dominates.
As a cash flow and income focused stock investor, I really don’t get the market valuation of Amazon. The stock trades at close to 500 times earnings per share and has always had an extremely high share value compared to its net income. However, Amazon has become and continues to grow as a major force in retail sales.
I personally would not buy into the sky-high valuation that Amazon trades at, but I do want to participate in the market dominance of the business and earn a return through auxiliary businesses that profit from Amazon’s success. I have dug around and found a few options where investors can participate in the Amazon story and earn an attractive dividend income stream in four “Accelerating Dividend Stocks” without overpaying.
I think we are all familiar with what Amazon does. It is the online marketer of a tremendous variety of products. The sales of those products require a robust Internet website and back end electronic services to process orders. The company then needs warehouses and shipping facilities to make sure the ordered items get quickly delivered to the buyers. Part of the issue with profitability at Amazon is the continued capital spending required to build the infrastructure needed to support an ever growing stream of orders and sales. Another growth offering is Amazon Web Services (AWS), which has become the largest public cloud solutions provider.
Income focused investors can participate in the Amazon story through real estate investment trusts (REITs) that provide facilities and services to Amazon or that help other companies work with the Amazon systems. Data center REITs own facilities where companies can either install their own data storage and communication platforms or they can have those services included in their lease agreements. This REIT subsector has been a hot place to invest compared to the entire group of stock market sectors and subsectors. The data center REITs can host AWS cloud service computers and they also provide global inter-connectivity for the companies that use AWS for their cloud storage needs. Two REITs have focused their offerings on supporting Amazon Web Services.
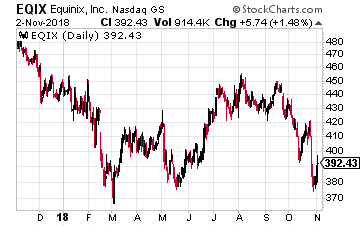 Equinix Inc (NASDAQ: EQIX) with a $27 billion market cap is one of the largest data center companies with 145 facilities located across the globe. In mid-2015, Equinix converted to REIT status, so investors should start to see more emphasis on dividends and dividend growth. In February 2016, the company increased its quarterly dividend by 3.6%. In its 2016 guidance, Equinix forecasts that adjusted funds from operations (AFFO) will grow by 17% in 2016. Since AFFO is the cash flow out of which companies pay dividends, investors can expect mid-teens payout growth going forward. EQIX currently yields 1.8%. This stock is up way big since I first recommended it back at the end of March, and I think data center REITs continue to offer a lot of upside.
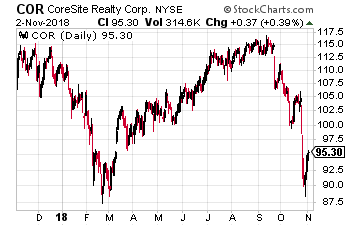 It is obvious that Amazon needs a tremendous amount of warehouse space. In those facilities the company stores its own inventories, inventories of third-party sellers on Amazon and completes its order fulfillment services. While Amazon currently owns the majority of its warehouse and fulfillment centers, the company also leases space from a few industrial property sector REITs.
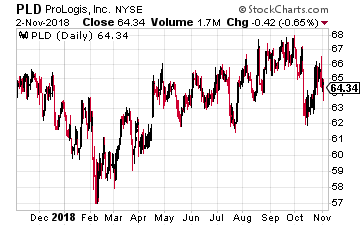 Prologis Inc. (NYSE: PLD) with a $26 billion market value is the largest industrial REIT. The company focuses on providing facilities for logistics services. In a recent presentation it was noted that e-commerce fulfillment services require three times the square footage compared to traditional storage and shipment of retail goods. E-commerce sales are forecast to double in the next five years. While it represents a small percentage of Prologis total revenue, Amazon is the REIT’s largest customer. Prologis has steadily grown core FFO per share and its dividend by an average 10% per year for the last five years. PLD yields 3.5%.
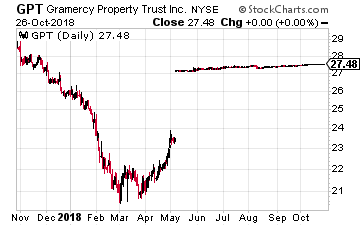 Gramercy Property Trust (NYSE: GPT) is a $4 billion diversified REIT that owns industrial, office, and specialty real estate assets. Amazon is Gramercy’s largest client in its industrial property portfolio, which is about one-third of the total asset portfolio. In late 2015, Gramercy completed a merger with a similar sized REIT. Now larger, the company is selling and buying properties to generate a more stable growth profile. Look for the dividend to start to grow in 2016. GPT yields 4.5%.
The industrial REITs offer possible upside if Amazon decides to monetize some of its owned warehouse assets. Owning warehouses is not the most efficient use of capital for an e-commerce company like Amazon. It would be a big positive for the REITs listed above if Amazon wanted to sell a warehouse… or 50.
These 5 stocks are all up double-digit percentages since I first recommended them in late March, and that is no coincidence. The power of a rising dividend and strong cashflow growth are on full display with these 5 stocks.
Finding stable companies that regularly increase their dividends like the five profiled above is the strategy that I use myself to produce superior results, no matter if the market moves up or down in the shorter term.
The combination of a high yield and regular dividend growth is what has given me the most consistent gains out of any strategy that I have tried over my decades-long investing career.
I call this system Accelerating Dividends and when you use it you can double your money in as little as four and a half years using safe dividend stocks just like I am.
You probably already know there are about 3,000 U.S. stocks that pay dividends, with some yielding 12%+ per year.
But it’s not the size of the dividend that counts, it’s whether those dividends are sustainable and rise over time, like the ones mentioned above.
Rising dividends propel share price returns and rapidly increases the cash income you earn on your investments. And, not only are companies with Accelerating Dividends more profitable than dividend stocks that don’t increase their payouts, they are safer too.
If you do not own any stocks with Accelerating Dividends or this is the first time you have heard of this powerful class of stocks, I urge you to read my new report that I just released.
My new investor briefing reveals the simple to use strategy behind Accelerating Dividends that shows you how to identify stocks that pay sustainable dividends with a track record of increasing frequently – no matter what the market does.