
Even in This Market, Bargains Remain
Greece Worries Fade as China Becomes More of a Concern: Expect Volatility to Increase
It certainly has been an interesting month since our last update. Greece pushed to the edge of the long feared “Grexit” before agreeing to concessions insisted on by the European Union for a new bailout package. The terms were tougher than what voters in Greece voted against via referendum just 10 days before the Greek parliament passed the measures. This most likely mean escalating tension and violence in Greece in the near term and in all probability a new government in that country by the end of the year.
A bigger worry is China, where a stock plunge wiped out over $3 trillion in market value in three weeks before authorities came in with extraordinary measures to reverse the decline. This is unlikely to be the last time we hear from the Middle Kingdom given an increasingly number of analysts and noted investors that are noting the Chinese market reminds them of the NASDAQ in late 1999/2000.
Obviously a market crash in the second largest economy and equity market in the world would have global implications and impact markets worldwide. The Chinese recently reported quarterly GDP growth of 7% and continue to post “official” growth in line with government projections albeit at the slowest rate since 1990. Even those figures have to be taken with a huge grain of salt.
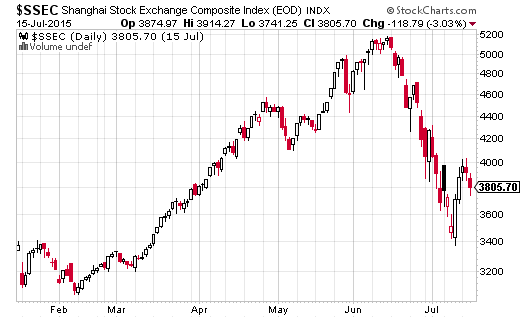
Copper is at six year lows and iron ore prices are down some 80% from their peak in 2011. I do not think either commodity would be at these levels if China was really growing at the levels they are reporting. In addition, the debt issue there cannot be ignored. Outstanding loans for companies and households stood at a record 207% of GDP at the end of June, up from 125% in 2008, data compiled by Bloomberg recently showed. Auto sales have slowed dramatically recently as well. This is my number one watch out for our markets right now and I am keeping a close eye on events there.
A nuclear deal with Iran was recently reached. Although the merits of the agreement will be hotly debated, and for good reasons: this will eventually bring more Iranian crude onto the global markets. This is another headwind the domestic energy sector could do without but should be good for the consumer discretionary and transportation sectors.
It is getting harder and harder to find good bargains in this market especially among the better known large cap names.
However, we are seeing some interesting plays in the small and mid-cap sectors of the market. The first half of the year has seen equities trading in mostly narrow trading range. The second half of the year will be interesting with possibly the first interest rate hike by the Federal Reserve since 2006. I have given up trying to predict the short term direction of the market but I do believe we will see higher volatility in the last half of 2015 than we did in the first six months of the year.
So let’s get started with this month’s issue. Click here for your copy.
Bret Jensen
Editor
The Turnaround Stock Report