
Sometimes the Market Will Ignore the Facts
“These are the times that try men’s souls. The summer soldier and the sunshine patriot will, in this crisis, shrink from the service of their country; but he that stands by it now, deserves the love and thanks of man and woman. Tyranny, like hell, is not easily conquered; yet we have this consolation with us, that the harder the conflict, the more glorious the triumph. What we obtain too cheap, we esteem too lightly: it is dearness only that gives everything its value. Heaven knows how to put a proper price upon its goods, and it would be strange indeed if so celestial an article as Freedom should not be highly rated” – Thomas Paine
After three weeks of watching the biotech sector being pummeled, I thought I would offer up an inspirational quote to start off our weekly update. After an encouraging rally that saw the sector rise some 20% to start the second quarter, that rally has gone into reverse over the past three weeks and we are once again near previous bear market lows.
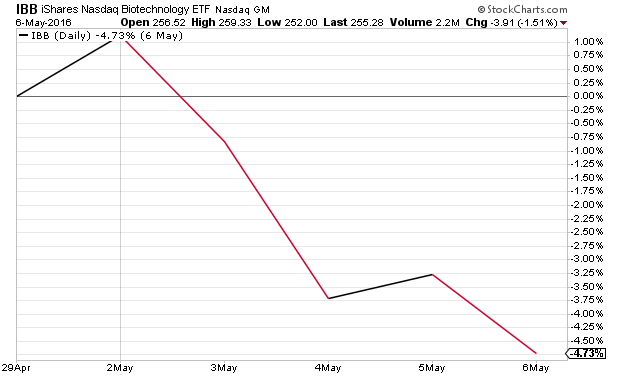
Earnings from most of the large industry players in general were solid with slight misses from Gilead Sciences (NASDAQ: GILD) and Alexion Pharmaceuticals (NASDAQ: ALXN) being some of the only exceptions among the top 25 large caps or so. Endo International (NASDAQ: ENDP), a mid-cap specialty/generic drug maker did plunge 40% on Friday after lowering its business guidance substantially. There was a knee-jerk reaction in the market (more on that below), but this seems more confined to Endo’s challenges not the industry in general.
M&A chatter seems to be picking up with a possible bidding war in the making for Medivation (NASDAQ: MDVN). A pick up in acquisitions would obviously be good for the “animal spirits” in the sector and something we are monitoring closely. Donald Trump becoming the presumptive nominee for the Republican Party was a negative in that many think this could put the House in play in the upcoming election, increasing the chances of detrimental legislative action for the industry in 2017. However, given how unpredictably this election has played out so far, I think it is way too early for any political conjecture at this point. The interesting part to this recent decline in biotech is one of the few parts of the market delivering any sort of growth right now. With almost 90% of S&P 500 companies reporting so far, profits have declined 7.1% this quarter year-over-year, the steepest quarterly loss since 2009. This is also the fourth straight quarter profits have declined, and fifth straight quarter revenues have fallen as well. Meanwhile, revenues for biotech companies within the S&P 500 are up some 12% this quarter from the same period a year ago. Sometimes the market does not care about facts, at least on a temporary basis.
Performance Update:
Our benchmark the iShares Nasdaq Biotechnology Index (NASDAQ:IBB) ETF, the largest ETF focused on the biotech sector with almost $9 billion in assets is now down 25.79% since we launched the Biotech Gems service at the start of May of 2015.
Our large cap core positions are now down 7.86% on average while our small cap portion of our portfolio is now down 30.65% on average, both not including dividends. Using the minimum 50% allocation recommended to our core positions gives us a blended loss of 19.26%, 653 basis points above our benchmark. The most conservative allocation of 75% dedicated to the large cap core positions results in a loss of 13.56%, precisely 1,223 basis points above the benchmark.
Portfolio News:
Endo’s revised guidance was due from the loss of exclusivity for its product Voltaren Gel, as well as increasing competition in the generic drug space. In was more than a knee jerk reaction in the market that larger drug makers like Mylan (NASDAQ:MYL), Allergan (NYSE:AGN), and Teva Pharmaceuticals (NYSE:TEVA) sold off on the news around Endo. Mylan reported numbers that beat bottom line expectations and affirmed guidance a few days earlier in the week. Allergan and Teva are much more diversified than Endo and haven’t even reported yet. If numbers come in as expected this week, I would not be surprised if we have some sort of snap back rally in these names especially Mylan who delivered solid results.
Our portfolio fell pretty much in line with the overall biotech indices. One exception was that of Relypsa (NASDAQ: RLYP) that sported deeper losses. The company arranged a $150 million loan to fund the rollout of its drug Veltassa. This is an interest only loan for the first 30 months which can be extended as interest only if Veltassa hits realistic sales goals. The market misinterpreted this as meaning a buyout is less likely in the foreseeable future. This is a wrong conclusion. The loan contains minor warrants (~.5% of outstanding float) and gives the company the ability to go it alone if need be. It certainly does not have to accept a lowball buyout offer now given the leverage in any negotiations. Nor does Relypsa need to significantly dilute its current shareholders by raising the same amount of the funding via a secondary offering.
It was a rollercoaster week for Pernix Therapeutics (NYSE: PTX). The stock exploded on the upside early in the week as it was disclosed that Steve Cohen’s Point 72 fund took a significant stake in the company. Unfortunately, the company gave those gains and then some back when quarterly results again disappointed. Management also withdrew forward guidance. At this point we are throwing in the towel on this one as management simply does not seem capable to deliver on the company’s promise that had me and other analysts so high on its future in its recent past.
We are removing it from the portfolio, although I am keeping my shares on the hopes that its debt can be refinanced and that is why Mr. Cohen took a position. However, there are better opportunities in this sector. I am evaluating three new possibilities and will send out a recommendation soon. Be on the lookout for it in your inbox.