
M&A Activity Seems to be Picking Up
Biotech finally broke out of an almost month-long slump and posted a solid week, easily outperforming the S&P 500. The Biotech Gems portfolio also had more than a solid week led by our small cap selections for the most part.
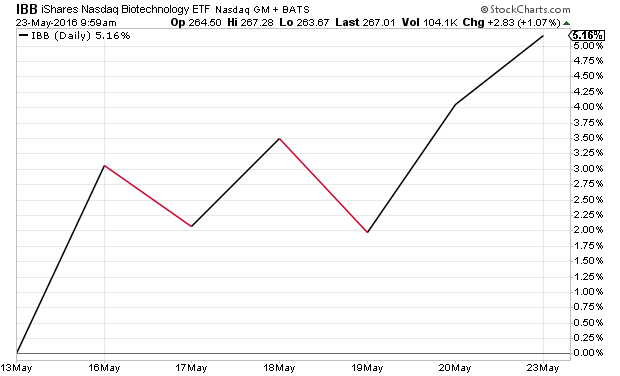
It seems what the sector needed was some pick up in M&A activity and it got that last Monday as Pfizer (NYSE: PFE) bought Anacor Pharmaceuticals (NASDAQ: ANAC) for over $5 billion which included a large 55% premium to the shareholders of Anacor. Hopefully, this will start a trend that would be a useful tailwind for this beaten down sector. If Medivation (NASDAQ: MDVN) gets purchased soon, as has been rumored for some time now, we might be able to put on our “rally caps” for more than a week at a time.
Performance Update:
Our benchmark the iShares Nasdaq Biotechnology ETF (NASDAQ: IBB), the largest ETF focused on the biotech sector with almost $9 billion in assets; is now down 23.20% since we launched the Biotech Gems service at the start of May of 2015.
Our large cap core positions are now down 6.60% on average while our small cap portion of our portfolio is now down 25.16% on average, both not including dividends. Using the minimum 50% allocation recommended to our core positions gives us a blended loss of 15.88%, 732 basis points above our benchmark. The most conservative allocation of 75% dedicated to the large cap core positions results in a loss of 11.24%, 1,196 basis points above the benchmark.
Portfolio News:
Aratana Therapeutics (NASDAQ: PETX), our newest selection, has acquitted itself well so far. The small biopharma garnered its second drug approval so far in 2016 last week as the FDA gave the green light for Entyce which is its appetite stimulator for dogs. Previously this year, Aratana received approval for Galliprant to treat osteoarthritis pain in dogs this March. Its third compound “Nocita” for post-op pain should be approved by the time 2016 comes to a close as well.
Portfolio News:
Relypsa (RLYP) could see some action this week as its potential competitor in the hyperkalemia market “ZS-9” has its PDUFA date with the FDA. I believe the most likely outcome for ZS-9 is approval with black box label for hypertension. That would mean ZS-9 would become the standard of care in the smaller Acute part of the hyperkalemia market while Veltassa dominates the larger chronic market. It would not surprise me if buyout talks get accelerated once the company and any potential suitors know the lay of the competitive land.
Also seeing good strength in our small cap portfolio last week were Eagle Pharma (NASDAQ: EGRX) which continues to recover from oversold levels. Inovio Pharmaceuticals (NYSE: INO) and Xencor (NASDAQ: XNCR) also had strong weeks. Synergy Pharmaceuticals (NASDAQ: SGYP) could be a mover this week as it reported positive results in a Phase III trial for its lead drug candidate Plecanatide after the market closed on Friday.