
What Happened to Eagle Pharmaceuticals?
The market posted its fifth straight week of gains, and stocks have now staged a valiant comeback from the panicked selling that began the year. A 40% rally in oil from its lows, improving sentiment in the high-yield credit markets, and dovish forecasting on interest rate hikes from the Federal Reserve this week all have been supportive of the rally.
Unfortunately, the biotech sector remains firmly mired in its biggest bear market since the financial crisis. The sector was down approximately three percent this week despite overall market rally. The consistent drip, drip, drip of bad news from Valeant Pharmaceuticals (NYSE: VRX), which now has lost more market value than Enron in six months, continues to cast a huge pall over the pharma and biotech sectors.
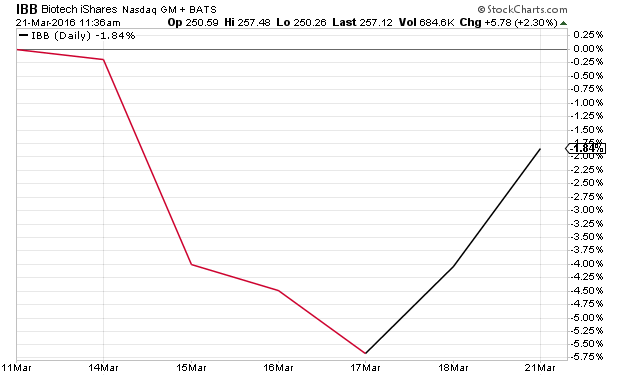
In addition, although demand in other high-yield credit markets has returned to a large degree, it has not yet to the biotech sector. Small caps continue to be hurt by the lack of interest in secondary offerings, debt deals, and IPOs in the space. This continues to hurt Pernix Therapeutics (NASDAQ: PTX) as concerns over its debt load persist despite its growing revenues and extremely low price to sales ratio. Synergy Pharmaceuticals (NASDAQ: SGYP) also took a hit this week as it converted some of its outstanding debt to equity. Although dilutive, it does significantly reduce its balance sheet risk.
Performance Update:
Our benchmark the iShares Nasdaq Biotechnology ETF (NYSE: IBB), the largest ETF focused on the biotech sector with almost $9 billion in assets, gave up some three percent this week and is now down 26.93% since we launched the Biotech Gems service at the start of May of 2015.
Our large cap core positions are now down exactly 8.56% on average while our small cap portion of our portfolio is now down 32.40% on average, both not including dividends. Using the minimum 50% allocation recommended to our core positions gives us a blended loss of 20.53%, 540 basis points above our benchmark. The most conservative allocation of 75% dedicated to the large cap core positions results in a loss of 14.52%, 1241 basis points above the benchmark.
Portfolio News:
Most of our portfolio drifted down with the biotech indices this week. Mylan (NASDAQ: MYL) continues to get hit every time additional bad news comes out around Valeant. Amgen (NASDAQ: AMGN) moved up slightly this week as it won an important patent case against Regeneron (NASDAQ: REGN) and Sanofi (NYSE: SNY) around its new cholesterol drug Repatha.
Gilead Science (NASDAQ: GILD) had another setback in developing its pipeline outside its core HCV and HIV franchises. The company announced it is curtailing six trials for its blood cancer drug Zydelig for additional indications due to adverse side effects. The stock was also up slightly on the week. This gives further emphasis for the company to make purchases using its massive $15 billion annual free cash flow. Given the carnage recently in the small and mid-cap portion of the biotech sector, it is a great time to have “dry powder” to put to use.
Eagle Pharmaceuticals (NASDAQ: EGRX) lost nearly 20% of its value in trading on Friday after the U.S. Food and Drug Administration rejected the firm’s application for approval of Kangio (an intravenous formulation of bivalirudin) for use as an anticoagulant in patients undergoing percutaneous coronary intervention.
But while this event was disappointing, the news doesn’t mean Eagle can’t work through the FDA’s concerns and eventually secure the drug’s approval. And more importantly, EGRX’s earnings and revenues are going to be driven in the short and medium term by sales of Bendaka, a just-launched (and much-improved) version of Treanda. Eagle rolled out Bendaka in conjunction with partner Teva Pharmaceuticals (NYSE: TEVA), and both companies seem aligned on moving Treanda patients onto the new product. Teva has some $800 million in annual Treanda annual revenues, and Eagle will receive 20% royalties on all Bendaka sales.
Eagle’s drug Ryanodex is also undergoing Phase II trials and has a good chance of winning approval for exertional heat stroke. I took the opportunity provided by the pullback Friday to double my stake in this promising biopharma. The stock sold for north of $100 last summer and even with the FDA’s hopefully temporary rejection of Kanglio, the company should still earn between $4 and $5 a share in FY2016 after doing just better than break even in FY2016. The stock is too cheap at under $45. Mizuho Securities five-star rated analyst (TipRanks) reiterated her Buy rating and $71 price target after the FDA news broke and I believe that is a fairer price for Eagle given its growth prospects.
Despite the overall negative week for biotech, we did have some bright spots in our portfolio. Tracon Pharmaceuticals (NASDAQ: TCON) and Lexicon Pharmaceuticals (NASDAQ: LXRX) were up some 10% on the week. Celsion (NASDAQ: CLSN), Inovio Pharmaceuticals (NASDAQ: INO), Synthetic Biologies (NYSE: SYN), Pacific Biosciences of California (NASDAQ: PACB) and TG Therapeutics (NASDAQ: TGTX) all bucked the downward tilt of trading in biotech to end up for the week.