
Politics As Usual on Drug Price “Gouging”
“If you put the federal government in charge of the Sahara Desert, in 5 years there’d be a shortage of sand.” – Milton Friedman
After months of being largely left alone by politicians this election year, the pharma and biotech sectors sold-off last week after pricing for the EpiPen became political fodder by former presidential candidate Bernie Sanders and current presidential candidate Hillary Clinton. The biotech indices had their worst week of performance so far in the second half of 2016 after the politicians scrutinized the price increase.
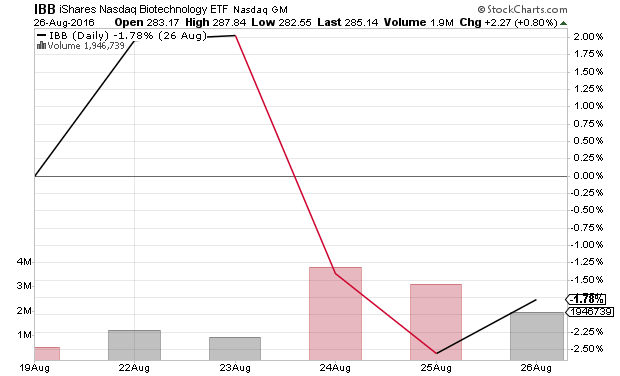
However, the slide was relatively muted compared to previous declines triggered by populist rants about drug price “gouging” over the past year. Perhaps the sector has become somewhat immune from these missives or maybe investors realize that Republicans will still control the House in 2017 and little action on the legislative front is likely to occur.
One thing that definitely helped the sector this week was an uptick of M&A activity, courtesy of Pfizer (NYSE: PFE). First it outbid Sanofi (NYSE: SFY) for a cool three billion dollars to winMedivation (NASDAQ: MDVN) in a bidding war that topped $14 billion last Monday. Not done yet for the week, the drug giant then bought the antibiotics business of AstraZeneca (NYSE: AZN). Before the Medivation deal, M&A deal volume was down more than 60% across the sector from the same period a year ago. Maybe this is the event that boosts “animal spirits” in M&A in the sector for the rest of 2016.
Performance Update:
Our benchmark the iShares Nasdaq Biotechnology ETF (NASDAQ: IBB), the largest ETF focused on the biotech sector with almost $9 billion in assets, is now down 17.11% since we launched the Biotech Gems service at the start of May of 2015.
Our large cap core positions are down 1.99% on average while the small cap portion of our portfolio has shown marked improvement and is now down 7.74% on average, both not including dividends. Using the minimum 50% allocation recommended to our core positions gives us a blended loss of 4.87%, 1,224 basis points above our benchmark. The most conservative allocation of 75% dedicated to the large cap core positions results in a loss of 3.43%, 1,368 basis points above the benchmark. As the numbers above prove, leveraging the careful selections and deep research that I do we can easily beat the benchmark over the course of many years.
Portfolio News:
As maker of the politically targeted EpiPen, Mylan (NASDAQ: MYL) obviously had a bad week. The management team was caught unaware of a predictable attack and then mangled their response to it, worsening the market’s reaction. I was happy to see they moved quickly to get out of the political storm but their execution and narrative left something to be desired. Hopefully, we have seen the worst of the reaction in the market as the shares are past cheap at eight times next year’s consensus earnings forecast.
Other than that, most of our holdings drifted down along with the biotech sector this week. TG Therapeutics (NASDAQ: TGTX) did manage to buck the downward trend by posting a solid gain. Its compound, TG-1011, was granted Orphan Drug status this week for a treatment of a rare disease. The company also was reiterated as a Buy at FBR Capital with a whopping $29 price target.
Ardelyx (NASDAQ: ARDX) also posted a nice gain for the week on no new news I could find. Perhaps investors are anticipating what could be a very exciting 2017 with the company submitting up to three separate New Drug Applications (NDAs) next year. The stock has been range bound throughout 2016 and now is at the top of that range. I will be watching closely to see if the shares start to break out in the weeks ahead.