
Memorial Production Partners Shows How Upstream MLPs Should Operate
I have written the following article for publication on the Seeking Alpha website. Since MEMP is a Dividend Hunter portfolio recommendation, I am sharing the article exclusively with my newsletter subscribers before I submit it to Seeking Alpha. As a Dividend Hunter subscriber, you get a two day first look at this article.
Out of the 15 upstream MLPs (as reported by MLP Protocol) only three have not recently reduced distribution rates paid to unit holders. Memorial Production Partners LP (Nasdaq: MEMP) is one of the three, and with its 2014 fourth quarter earnings report and 2015 guidance, the company expects to maintain the current distributions to investors. Also, MEMP now is the first to announce an acquisition deal in the new, low energy price environment. Memorial has put its business together to be able to both maintain its distribution rate and grow the business in this period of low energy prices. Now that Memorial has released its 2014 Q4 results and 2015 guidance, I will cover the high points of how the MEMP management team expects to maintain its current distribution rate through 2015 and into future years.
The operations and finance plan for Memorial Production Partners can be covered as a series of bullet points. These points add up to a company that has managed its business to do what investors expect an upstream MLP to do: Maintain a high distribution rate even as energy commodity prices fluctuate.
- Profitable Production Spending at Current Energy Prices. In East Texas, MEMP expects to complete 24 new wells in 2015. Based on current, unhedged energy prices, the capex spending on these wells generate a 30% rate of return. Total production across the company’s operations is forecast to grow by 13% in 2015.
- Reduced Capital Spending. For 2015, MEMP plans to reduce its capital spending by 29%, down to a $200 million midpoint. About half of the capital spending budget is for maintenance capex. The company still plans to increase total production by 13% this year.
- Unit Buyback Success. When every company in the energy sector was going down, the MEMP board authorized a $150 million unit buyback. In Q4 the company spent $41 million to buy in 2.8 million units for an average cost of $14.64 per unit. At that price, MEMP yielded 15%, a pretty nice return on capital.
- Sector’s Strongest Hedge Position. Memorial’s business plan has been to hedge most of its forecast oil and gas production 3 to 6 years out. Currently natural gas hedges go out to 2019, crude oil through 2018, and NGL hedges extend into 2017. Management notes that the company is “fully hedged to our maximum capability” for these periods. For 2015, 80% of forecast production for all energy types is hedged with a weighted average fixed floor price of $7.78/MMbtu.
- Low Operating Costs. In the earnings conference call management stated that MEMP has an all-in operating cost of $3.00/MMbtu. While not included in the 2015 guidance or forecasts, management noted that costs are falling and they expect the effects of lower costs to improve results as the year moves on.
These factors allow Memorial Production Partners to provide 2015 midpoint EBITDA guidance of $399 million, up from $310 million of EBITDA generated in 2014. Distributable cash flow guidance of $185 million, up from $138 million. The 2014 Q4 distributions paid to LP units annualized equals $184.5 million. That looks like 1.0 times coverage for this year. During the conference call management expressed their confidence in maintaining distributions to be paid to investors this year. They also stated that DCF coverage would increase in the second half of 2015.
First Upstream MLP Acquisition
The savvy management style of Memorial Production Partners shows in the company’s first acquisition in the current low energy price environment. The partnership made an exchange with its sponsor, Memorial Resource Development Corp., receiving properties primarily in Eastern Texas with approximately 165 net operating wells. MEMP will transfer to its sponsor other non-operating properties (5 net wells) in the same area and pay $73 million. With the transaction, MEMP will see an immediate 300% production increase from the field.
Bringing the Unit Value in Line With Potential
The market has realized that Memorial Production Partners is not like the other upstream MLPs that have slashed distribution rates, and can sustain its existing distribution rate in the current energy commodity environment of $50 crude oil and sub-$3.00 natural gas. As a result, MEMP is one of the top performing MLPs, year-to-date, with its unit price up 25% since the first of the year.
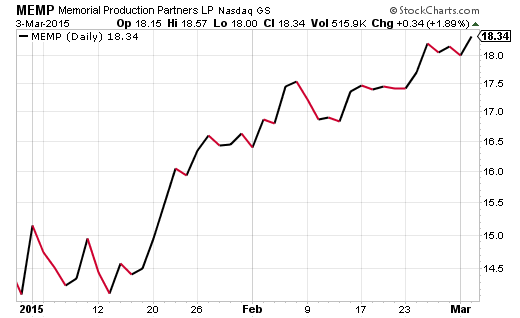
However, at $18.34, MEMP still yields 12%. The 12% yield level seems to have become the new 8% (the yield for the larger upstream MLPs for most of 2014) and most of MEMP’s peers are yielding in that low double digits range. I think that the management chops shown by Memorial to sustain its EBITDA and cash flow even with crude down 50% and natural gas down a third deserves a premium in the market place. I think the probability is high that MEMP will yield below 10% later in 2015. This would put the unit price up another 20% to $22 or better.